All Categories
Featured
Table of Contents
- – Understanding the 2026 Medicare Advantage Envi...
- – Network Restrictions and Geographic Flexibility
- – The $2,000 Out-of-Pocket Cap on Prescription ...
- – Evaluating Supplemental Benefits in 2026
- – Dental and Vision Nuances
- – Life Insurance as a Financial Companion
- – Final Expense Insurance for Seniors
- – Comparison Strategies for the 2026 Enrollment ...
- – Key Factors to Watch
- – Regional Trends in California and Beyond
- – The Role of Independent Advice
- – Preparing for the 2026 Enrollment Window
Understanding the 2026 Medicare Advantage Environment
The selection process for 2026 Medicare Advantage plans requires a shift in how beneficiaries evaluate their healthcare coverage. Many changes introduced by recent federal legislation have fully matured this year, affecting how private insurers structure their Part C offerings. For residents in Compton, these shifts mean that price tags on monthly premiums are no longer the only factor to consider. The interaction between medical networks, prescription drug costs, and supplemental benefits has become more complex.
Medicare Advantage, or Part C, remains a popular alternative to Original Medicare because it bundles Part A, Part B, and usually Part D into a single plan. In 2026, the focus has moved toward value-based care. This means insurers are more concerned with long-term health outcomes rather than just paying for individual doctor visits. Those looking for Term Life Insurance must look closely at how these plans manage chronic conditions and preventive screenings.
Network Restrictions and Geographic Flexibility
Doctor networks are tighter this year. Many carriers have narrowed their lists of preferred providers to keep costs down in the face of rising medical inflation. Selecting a plan in Compton requires verifying that specialists and hospitals are still within the network for 2026. An HMO (Health Maintenance Organization) typically offers lower costs but requires referrals and staying within a strict network. PPOs (Preferred Provider Organizations) offer more flexibility but often come with higher out-of-pocket costs if you see someone out of network.
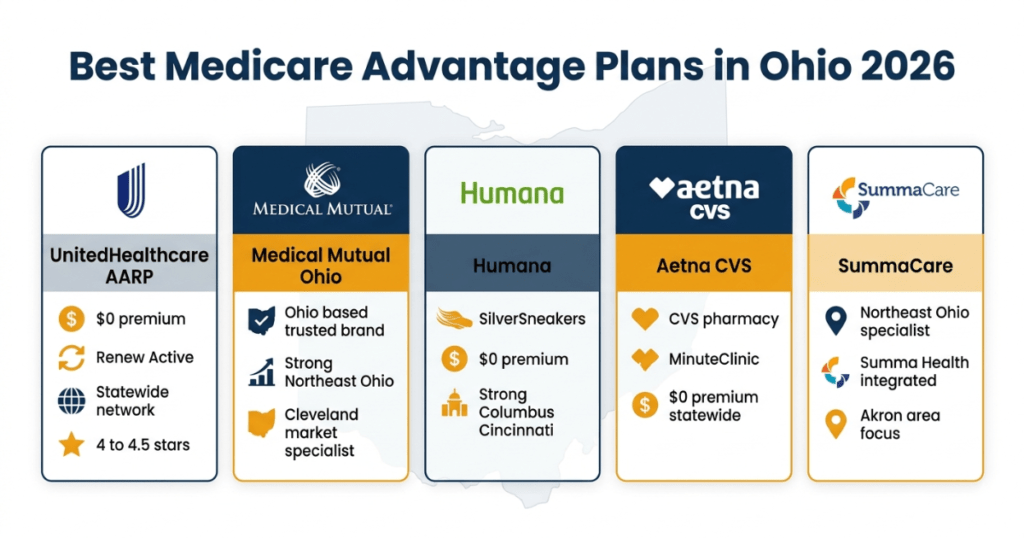
Searching for Harmony SoCal Insurance Services in Compton involves comparing the star ratings of various regional carriers. These ratings, updated for 2026, reflect member satisfaction and the quality of care provided over the last year. A plan with a high star rating might offer better access to specialists in areas like Huntington Beach or Anaheim, where medical groups are highly competitive.
The $2,000 Out-of-Pocket Cap on Prescription Drugs
The most significant change for 2026 is the stabilization of the $2,000 out-of-pocket cap for prescription drugs under Part D. This cap, which applies to Medicare Advantage plans with integrated drug coverage, provides a massive financial relief for seniors on expensive maintenance medications. Once a member spends $2,000 on covered drugs, they pay nothing for the rest of the year.
Reliability in Harmony SoCal Insurance Services Protection remains a top priority for those entering the 2026 enrollment period. While the cap is a benefit, some insurers have responded by increasing premiums or changing their formularies. A medication that was on a "Tier 2" list in previous years might have moved to "Tier 3" for 2026, meaning higher costs before the cap is reached. It is essential to run a personal drug list through the 2026 plan finder to see exactly how each plan treats specific prescriptions.
Evaluating Supplemental Benefits in 2026
Extra benefits like dental, vision, and hearing have long been the "hook" for Medicare Advantage plans. However, in 2026, many carriers have adjusted these perks. Some plans have moved from "unlimited" dental cleanings to a set dollar amount for the year. Others have introduced debit cards that can be used for over-the-counter (OTC) items or even healthy groceries for those with certain chronic conditions.
Beneficiaries in Compton should check if their preferred dentist or optometrist accepts the specific insurance being considered. It is common for a plan to offer "comprehensive" dental but only through a very small network of providers. If your dentist in Chula Vista or Corona is not on that list, the benefit might be useless to you.
Dental and Vision Nuances
Standard Part C plans often include basic cleanings and eye exams. In 2026, more plans are offering "flex allowances" that allow the member to choose how to spend their benefit dollars. This flexibility is helpful for those who might need expensive hearing aids one year but want to focus on new glasses the next. These allowances are usually "use it or lose it," so planning medical appointments early in the year is a smart strategy for 2026.
Life Insurance as a Financial Companion
As healthcare costs continue to fluctuate, many seniors are looking at life insurance as a way to protect their estates and cover final expenses. While Medicare Advantage handles the medical side, it does not cover funeral costs or provide a cash benefit to heirs. Integrating a life insurance policy with a 2026 Medicare plan creates a more complete financial strategy.
Harmony SoCal Insurance Services Medicare Part D acts as a secondary layer of protection against high deductibles and unexpected end-of-life expenses. For those in Compton, whole life insurance remains a common choice because it builds cash value and the premiums remain level. Term life insurance is also an option for those who only need coverage for a specific period, such as until a mortgage is paid off.
Final Expense Insurance for Seniors
Final expense insurance, often called "burial insurance," is a type of whole life policy with a smaller death benefit, usually between $5,000 and $25,000. These policies are easier to qualify for than traditional life insurance, often requiring no medical exam. This is particularly useful for seniors with pre-existing conditions that might make other policies too expensive. In 2026, these products have become more streamlined, with many offering instant approval online.
Comparison Strategies for the 2026 Enrollment Period
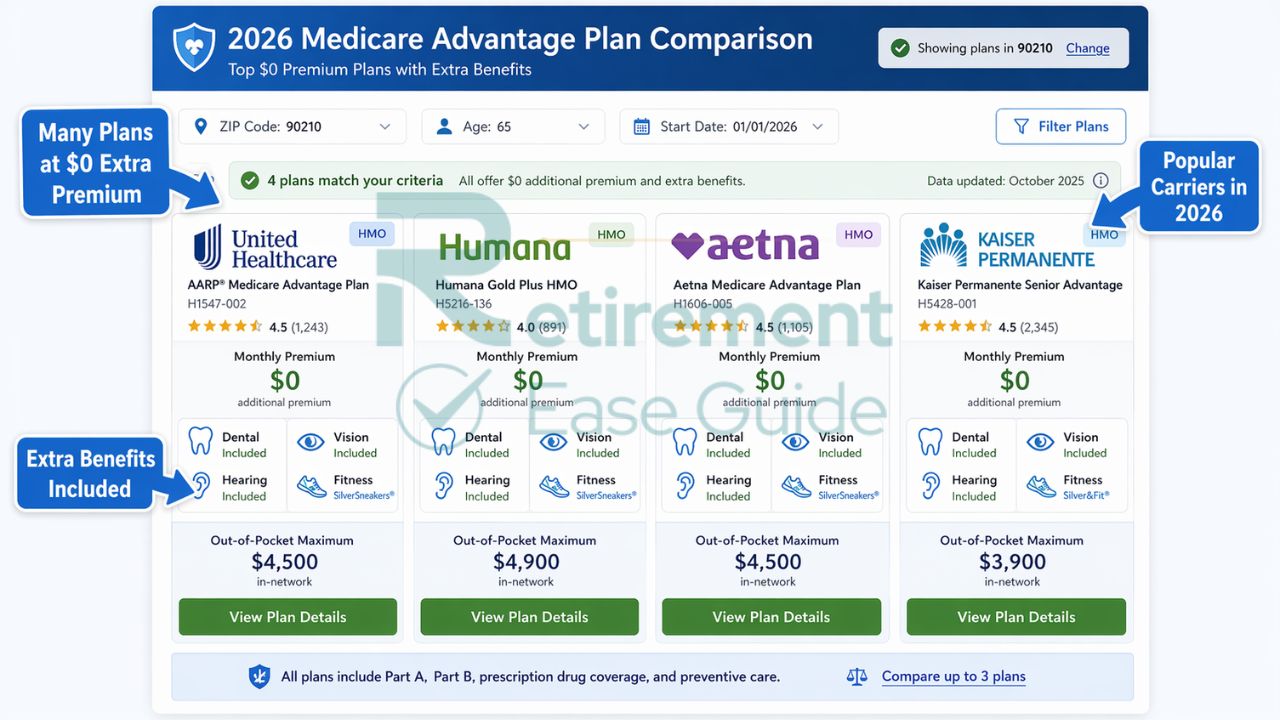
The Annual Enrollment Period (AEP) is the window to make changes. For 2026, this period is more active than usual due to the shifting plan structures. To compare Term Life Insurance effectively, start with the "Summary of Benefits" document for each plan. This document lists the costs for common services like hospital stays, primary care visits, and diagnostic tests.
A common mistake is focusing only on the monthly premium. A "zero-premium" plan might look attractive, but if the co-pay for a specialist visit is $50 and you see a specialist twice a month, you are actually paying $100 per month for that plan. Conversely, a plan with a $30 premium might have $10 co-pays, making it the cheaper option in the long run.
Key Factors to Watch
- Maximum Out-of-Pocket (MOOP) Limit: This is the absolute most you will pay for medical services in 2026. For many plans, this limit is around $4,000 to $8,000.
- Prior Authorization Requirements: Some plans require the insurance company to approve a procedure before the doctor can perform it. Tighter restrictions are expected in 2026.
- Telehealth Access: Virtual visits have become a standard part of Medicare Advantage. Ensure the plan supports the technology you are comfortable using.
Regional Trends in California and Beyond
In markets like Escondido and Huntington Beach, competition between insurers remains high. This competition benefits the consumer, as plans often try to "out-perk" each other with things like gym memberships or transportation to medical appointments. However, regional consolidation has also occurred. Some smaller insurers have been bought by larger national brands, which can lead to changes in how claims are processed.
Individuals living in Compton should also be aware of "Special Needs Plans" (SNPs). These are Medicare Advantage plans tailored for people with specific diseases like diabetes or heart failure, or for those who are dual-eligible for Medicare and Medicaid. These plans often provide much lower costs and more specialized care coordination than a standard Part C plan.
The Role of Independent Advice
Because there are so many moving parts in the 2026 Medicare Advantage market, many people find it helpful to speak with an independent professional who can compare multiple carriers. These individuals can run a cost analysis based on specific doctors and medications. They can also explain how a life insurance policy might fit into the broader goal of protecting family assets.
Preparing for the 2026 Enrollment Window
Reviewing your "Annual Notice of Change" (ANOC) is the first step. This document arrives in late September and outlines exactly how your current plan will change for the upcoming year. If your premium is going up or your favorite doctor is leaving the network, 2026 is the time to shop around.
The 2026 Medicare Advantage market is designed to reward those who do their homework. By looking at the drug caps, network changes, and supplemental benefits together, residents in Compton can secure a plan that provides both health and financial security. Pairing these choices with a stable life insurance policy ensures that both the present and the future are well-protected. Use the available tools and data to make an informed decision before the enrollment deadline passes.

Table of Contents
- – Understanding the 2026 Medicare Advantage Envi...
- – Network Restrictions and Geographic Flexibility
- – The $2,000 Out-of-Pocket Cap on Prescription ...
- – Evaluating Supplemental Benefits in 2026
- – Dental and Vision Nuances
- – Life Insurance as a Financial Companion
- – Final Expense Insurance for Seniors
- – Comparison Strategies for the 2026 Enrollment ...
- – Key Factors to Watch
- – Regional Trends in California and Beyond
- – The Role of Independent Advice
- – Preparing for the 2026 Enrollment Window
Latest Posts
Why Manhattan Beach Residents Are Reviewing Medigap Options Today
Navigating EPO Family Plans in Compton
Latest Posts
Why Manhattan Beach Residents Are Reviewing Medigap Options Today
Navigating EPO Family Plans in Compton