All Categories
Featured

Life Insurance for Service Members
1 Investopedia - How Whole Life Insurance Coverage Works. Upgraded May 7, 2025. . Accessed June 18, 2026. 2 Thrivent Whole life insurance coverage: Pros, cons & who it's ideal for. Upgraded March 10, 2026. . Accessed June 18, 2026. 3 Forbes - What Is Whole Life Insurance Coverage? (& How Does it Work?) Updated December 18, 2024.

4 Forbes - What Is Variable Life Insurance? Material within this short article is offered for general educational functions and is not provided as tax, legal, health, or financial advice for any individual or for any specific scenario.
For total details, including availability and expenses of Aflac insurance coverage, please call your local Aflac agent/producer. Aflac life prepares A68000 series/Term Life: In Arkansas, Idaho, Oklahoma, Oregon, Texas, Pennsylvania & Virginia, Policies: ICC1368200, ICC1368300, ICC1368400. In Delaware, Policies A68200, A68300 & A68400. In New York City, Policies NY68200, NY68300 and NY68400.
How Whole Life Insurance Works
In Delaware, Policy A68100. In New York, Policy NYR68100. B60000/Term Life: In Arkansas, Oklahoma, Pennsylvania, Texas & Virginia, Policies ICC18B60200, ICC18B60300, & ICC18B60400. Not offered in Delaware, Idaho, New York and Oregon. Whole Life: In Arkansas, Oklahoma, Pennsylvania, Texas & Virginia, Policies: ICC18B60C10, ICC18B60100. Not available in Delaware, Idaho, New York City and Oregon.
In Delaware, Policy Q60200M. In New York City, Policy: NYQ60200M. Not offered in Virginia. Whole Life: In Arkansas, Delaware & Oregon Policy Q60100M. In Idaho, Policy Q60100MID. In Oklahoma, Policy Q60100MOK. In New York, Policy: NYQ60100M. Not offered in Virginia. In AR, DE, ID, OK and VA: Policies ICC21-AFLLBL21 and ICC21-AFLRPL21; and Riders ICC21-AFLABR22, ICC21-AFLADB22, and ICC21-AFLCDR22.

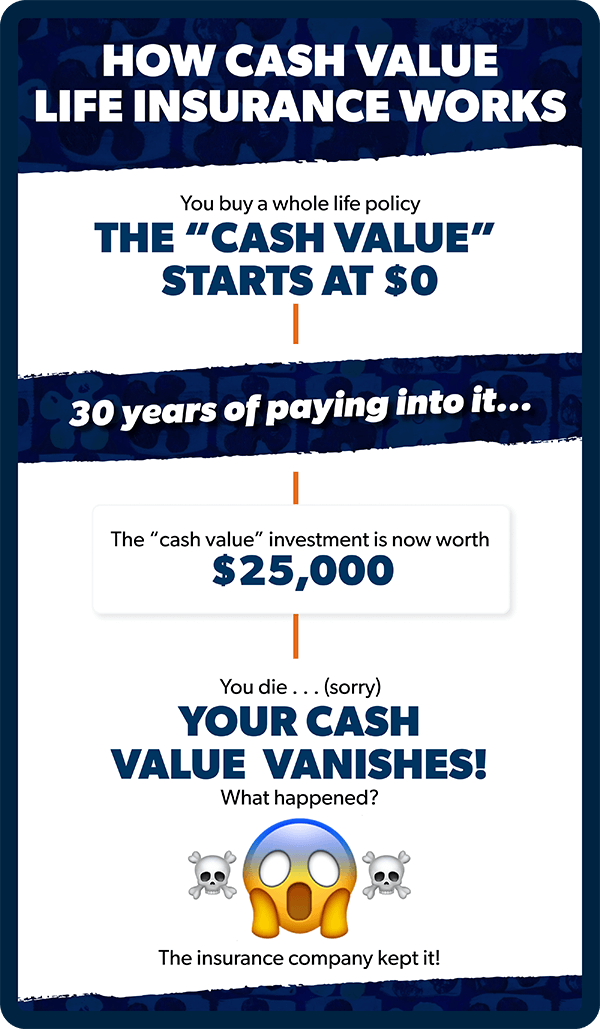
In this short article, we describe what entire life insurance coverage is and compare it to term life insurance coverage, as well as universal life and variable life insurance. Whole life insurance coverage is one kind of permanent insurance and is very different from term life insurance, which offers protection for a given period just and does not develop money value. If term life insurance is the most common type of life insurance coverage, whole life insurance is the earliest form of irreversible life insurance coverage.
The larger your cash value, the larger the loan you can take. You can utilize your money value to supplement your other retirement earnings. Whole life insurance is the only type of life insurance coverage that guarantees of the following: The death benefit will not decrease The policy will not expire as long as premiums are paid Your premiums will not
Insurance in Ontario CAgo up Your costs will never increase The insurance provider guarantees that the cash value of your entire life insurance coverage policy will grow over time. identify how much your money value should grow based on current rate of interest, which, obviously, differ gradually. permit you to invest funds in policy subaccounts, similar to shared funds. Your money value will increase orreduce, depending upon the performance of these subaccounts. What happens if efficiency of the cash worth of your universal or variable life policy drops? Who needs to ante up more premium to keep your policy in force? You do. Neither choice is good. If you have a whole life policy, you will not need to make those awful options. The premium, cash value, and death advantage are all ensured. And did you know you can discover precisely what your surefire premium, cash value and survivor benefit will be at any time before you decide if it makes sense to start an entire life policy? Just ask for a FREE, no-obligation Analysis here to take the first action. In such a way, it resembles getting an income tax refund. Now, dividends are not ensured. It's conceivable an insurance provider could have a horrible, awful, no excellent, very bad year . In fact, that's what the company prepares for. And every year that'sbetter than they prepared, they can pay a dividend. Get Your FREE Report! Get instantaneous access to the FREE 18-page Special Report that exposes how super-charged dividend paying whole life insurance lets you bypass Wall Street, fire your banker, and take control of your monetary future. You get to tell the insurance company what to do with your dividend. and this just may be the neatest thing because cupcakesyou can have them use your dividend to purchase more insurance for you insurance coverage you'll never need to pay another premium for again. Think about that! You can buy additional insurance coverage that's paid up, suggesting no more premiums will be due on that additionever. If that advises you of the eighth marvel of the worldcompound interestthat's because the concept is precisely the exact same. Just paid up whole life insurance coverage additions develop both your policy's money worth and your death benefit. You can find out more here about dividend-paying whole life insurance, which lots of people discover particularly exciting. Term life insurance premiums go upsometimes drasticallywith every brand-new term, because much of the expense of insurance is based upon how most likely you are to die at an offered age, and as you grow older, that likelihood goes up. Universal and variable insurance coverage premiums can increase, tooagain, in some cases drasticallyif cash worth drops dueto low rates of interest or bad investment performance. You may be asking, "If it costs more to insure my life with every passing year, how can a life insurance coverage company assure my premiums will never ever go up?" The answer is elegantly simpleand it helps discuss why whole life insurance is more pricey than term insurance coverage in the early years of the policy.

Latest Posts

Navigating Medicare Part D

Why Burial Insurance Covers Your Family's Future
Life Insurance for Service Members